 TOPICS

Finite Difference
The finite difference is the discrete analog of the derivative. The finite forward difference of a function
 is defined as
 |
(1)
|
and the finite backward difference as
 |
(2)
|
The forward finite difference is implemented in the Wolfram Language as DifferenceDelta[f, i].
If the values are tabulated at spacings  , then the notation
 |
(3)
|
is used. The  th
forward difference would then be written as
 , and similarly, the
 th backward difference
as
 .
However, when  is viewed as a discretization of the continuous function
 , then the finite difference is sometimes written
 |  |  |
(4)
|
 |  | *f(x),](https://mathworld.wolfram.com/images/equations/FiniteDifference/Inline14.svg) |
(5)
|
where  denotes convolution and
](https://mathworld.wolfram.com/images/equations/FiniteDifference/Inline16.svg) is the odd impulse pair. The finite difference operator
can therefore be written
 |
(6)
|
An  th
power has a constant
 th finite difference. For example, take
 and make a difference table,
 |
(7)
|
The  column is the constant 6.
Finite difference formulas can be very useful for extrapolating a finite amount of data in an attempt to find the general term. Specifically, if a function  is known at only a few discrete values
 , 1, 2, ... and it is desired to determine the analytical
form of
 ,
the following procedure can be used if
 is assumed to be a polynomial
function. Denote the
 th
value in the sequence of interest by
 . Then define
 as the forward difference
 ,
 as the second forward
difference
 ,
etc., constructing a table as follows
 |
(8)
|
 |
(9)
|
 |
(10)
|
 |
(11)
|
Continue constructing the difference table through the last available row. The unique polynomial of degree at most  interpolating the
 values
 ,
 , ...,
 is then given by
 |  |  |
(12)
|
 |  |  |
(13)
|
Here  ,
so
 ,
 ,
etc. This equation is called Newton's
forward difference formula. To see a particular example, consider a sequence
with first few values of 1, 19, 143, 607, 1789, 4211, and 8539. The difference table
is then given by
 |
(14)
|
Reading off the first number in each row gives  ,
 ,
 ,
 ,
 . Plugging these in gives the equation
 |  |  |
(15)
|
 |  |  |
(16)
|
which indeed fits the original data exactly.
Formulas for the derivatives are given by
 |  |  |
(17)
|
 |  |  |
(18)
|
 |  |  |
(19)
|
 |  |  |
(20)
|
 |  |  |
(21)
|
 |  |  |
(22)
|
 |  |  |
(23)
|
 |  |  |
(24)
|
 |  |  |
(25)
|
 |  |  |
(26)
|
 |  | 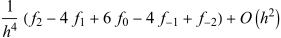 |
(27)
|
(Beyer 1987, pp. 449-451; Zwillinger 1995, p. 705).
Formulas for integrals of finite differences
 |
(28)
|
are given by Beyer (1987, pp. 455-456).
Finite differences lead to difference equations, finite analogs of differential equations. In fact, umbral calculus displays many elegant analogs of well-known identities for continuous functions. Common finite difference schemes for partial differential equations include the so-called Crank-Nicolson, Du Fort-Frankel, and Laasonen methods.
See also
Backward Difference, Bessel's Finite Difference Formula, Derivative, Difference Equation, Difference Table, Everett's Formula, Finite Element Method, Forward Difference, Gauss's Backward Formula, Gauss's Forward Formula, Interpolation, Jackson's Difference Fan, Newton-Cotes Formulas, Newton's Backward Difference Formula, Newton's Divided Difference Interpolation Formula, Newton's Forward Difference Formula, Quotient-Difference Table, Recurrence Equation, Steffenson's Formula, Stirling's Finite Difference Formula, Umbral CalculusExplore with Wolfram|Alpha

References
Abramowitz, M. and Stegun, I. A. (Eds.). "Differences." §25.1 in Handbook of Mathematical Functions with Formulas, Graphs, and Mathematical Tables, 9th printing. New York: Dover, pp. 877-878, 1972.Beyer, W. H. CRC Standard Mathematical Tables, 28th ed. Boca Raton, FL: CRC Press, pp. 429-515, 1987.Boole, G. and Moulton, J. F. A Treatise on the Calculus of Finite Differences, 2nd rev. ed. New York: Dover, 1960.Conway, J. H. and Guy, R. K. "Newton's Useful Little Formula." In The Book of Numbers. New York: Springer-Verlag, pp. 81-83, 1996.Fornberg, B. "Calculation of Weights in Finite Difference Formulas." SIAM Rev. 40, 685-691, 1998.Iyanaga, S. and Kawada, Y. (Eds.). "Interpolation." Appendix A, Table 21 in Encyclopedic Dictionary of Mathematics. Cambridge, MA: MIT Press, pp. 1482-1483, 1980.Jordan, C. Calculus of Finite Differences, 3rd ed. New York: Chelsea, 1965.Levy, H. and Lessman, F. Finite Difference Equations. New York: Dover, 1992.Milne-Thomson, L. M. The Calculus of Finite Differences. London, England: Macmillan, 1951.Richardson, C. H. An Introduction to the Calculus of Finite Differences. New York: Van Nostrand, 1954.Spiegel, M. Calculus of Finite Differences and Differential Equations. New York: McGraw-Hill, 1971.Stirling, J. Methodus differentialis, sive tractatus de summation et interpolation serierum infinitarium. London, England, 1730. English translation: The Differential Method: A Treatise of the Summation and Interpolation of Infinite Series (Trans. J. Holliday). 1749.Tweddle, C. James Stirling: A Sketch of His Life and Works along with His Scientific Correspondence. Oxford, England: Oxford University Press, pp. 30-45, 1922.Weisstein, E. W. "Books about Finite Difference Equations." http://www.ericweisstein.com/encyclopedias/books/FiniteDifferenceEquations.html.Zwillinger, D. (Ed.). "Difference Equations" and "Numerical Differentiation." §3.9 and 8.3.2 in CRC Standard Mathematical Tables and Formulae. Boca Raton, FL: CRC Press, pp. 228-235 and 705-705, 1995.Referenced on Wolfram|Alpha
Finite DifferenceCite this as:
Weisstein, Eric W. "Finite Difference." From MathWorld--A Wolfram Resource. https://mathworld.wolfram.com/FiniteDifference.html